Sherwin-Williams
Get more value out of your Sherwin-Williams benefits, without the tax surprises
Sherwin-Williams pays its people in more ways than a paycheck: performance RSUs, stock options, a pension plan, and deferred compensation. Tempo is a fiduciary advisory firm that helps SHW employees turn those pieces into one plan.
Prefer to talk it through? Match with an advisor →
Free Guide
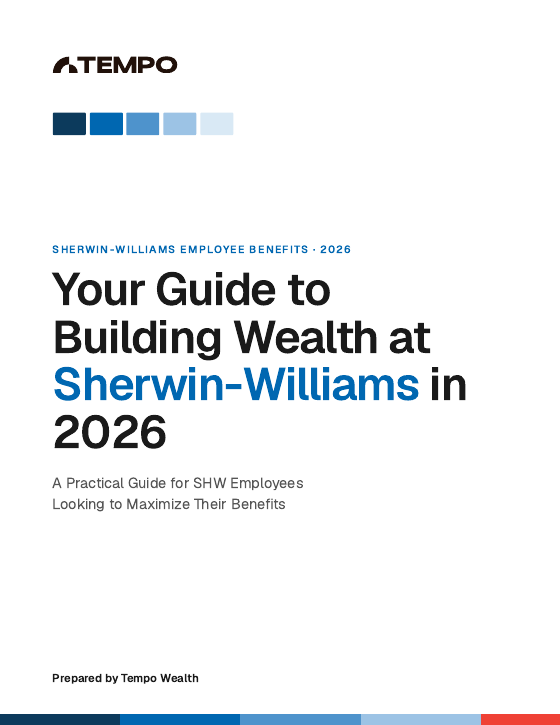
How to Build Wealth at Sherwin-Williams in 2026
- Options, RSUs, and the withholding gap
- Deferred comp, NUA, and your HSA
- Balancing the 401(k) with the rest of your benefits
Got it! You should be redirected momentarily. If not, click here to go directly to the download page.
Oops! Something went wrong while submitting the form.
Sherwin-Williams has always been about helping people create something lasting and the same goes for their employee benefits. The challenge is knowing how to put it all together in a way that supports your long-term goals.
Where the SHW package gets complicated
Sherwin-Williams gives you real wealth-building tools. Most of them have implications that only show up at tax time or in retirement. These are the places where planning tends to matter most for SHW employees.
SHW RSUs and options: the tax timing problem
Performance RSUs pay out at 0 to 200% of target based on company results, and vested shares are taxed as ordinary income with just 22% federal withholding for most employees. If your real rate is higher, the difference lands in April. Stock options add their own timing questions, including AMT exposure on ISO exercises.
A 401(k) with company stock inside it
SHW's plan is an Employee Stock Purchase and Savings Plan — company stock can build up inside your 401(k), which is what puts NUA on the table later. Add the 6% match, a $24,500 deferral limit for 2026, and catch-up contributions that now must go Roth for most higher earners, and the order you fill these buckets decides how hard the plan works.
Deferred comp: a payout election you live with
The Deferred Compensation plan lets high earners delay income, with payouts as a lump sum or annual installments over 2 to 15 years. The schedule you elect drives your tax brackets in retirement and can even decide which state taxes the income. It is chosen in advance and hard to undo.
NUA on SHW stock in your 401(k)
If you hold company stock inside the plan, Net Unrealized Appreciation rules can move years of growth from ordinary income rates to long-term capital gains rates at retirement. The catch: the rollout has to be sequenced correctly, and a routine rollover can forfeit the option entirely.
Our work with SHW employees
The team at Tempo has worked with stock-eligible employees at SHW for years, coordinating the 401(k), stock awards, and insurance coverage with tax and retirement income planning. Our role is to connect the dots so your benefits work as one plan rather than a set of separate decisions.

Coordinating RSU vests with the rest of your income
We map vesting dates against salary, bonus, and option exercises, and estimate the withholding gap ahead of time so it can be planned for rather than discovered at filing time.
Choosing a deferred comp payout schedule
We model lump sum against installment payouts of 2 to 15 years before the election window closes, including the state tax angle for employees considering a move in retirement.
Deciding when NUA beats a rollover
We run the numbers lot by lot on SHW stock in the 401(k) before any rollover paperwork gets signed, to evaluate whether NUA treatment may be advantageous for your position.
Making the pension and 401(k) work together
SHW's pension contributions scale with your age and years of service. We fold them into the retirement income plan rather than treating them as a footnote.
Scenarios we plan for at Sherwin-Williams
If you are a manager or executive at SHW, especially in the stretch between 45 and 60 when these decisions stop being theoretical, some version of one of these is probably on your desk right now.
Common Starting Point
“My RSU vest pushed my income up and the withholding did not keep up.”
SHW withholds 22% federal on most vested RSUs, and higher withholding only kicks in above $1M in supplemental wages. For most executives the real marginal rate sits well above 22%, and the difference comes due at filing time.
How Tempo approaches it: We estimate the potential gap before each vest cycle and plan for it with cash set aside or quarterly payments, so it is identified before the bill arrives.
Retirement Window · 55+
“I am 55 with SHW stock in my 401(k). Should I use NUA when I retire?”
NUA treatment can move years of SHW growth from ordinary income rates to long-term capital gains rates, but it only works if the distribution is sequenced correctly at separation.
How Tempo approaches it: We analyze cost basis lot by lot, compare NUA against a full rollover, and evaluate whether the election may be advantageous given your other income.
Time-Sensitive · Election Window
“Enrollment is coming and I need to pick my deferred comp payout schedule.”
The schedule you elect decides how deferred income stacks on top of Social Security, pension payments, and portfolio withdrawals, and which state gets to tax it if you move.
How Tempo approaches it: We model the payout options against your projected brackets and residency plans before the window closes, not after.
Concentration
“I want to retire by 60, but a big share of my net worth is SHW stock.”
Options, performance RSUs, and company stock in the 401(k) add up faster than most people track. A drawdown in a single ticker should not be able to move your retirement date.
How Tempo approaches it: We build a diversification schedule that respects trading windows, tax cost, and the date you actually want to stop working.
Sherwin-Williams NUA calculator: compare an election against a rollover
If you hold Sherwin-Williams stock inside your 401(k), Net Unrealized Appreciation rules may allow the growth to be taxed at long-term capital gains rates instead of ordinary income rates. The sliders start on a sample position; move them to match yours.
Tax assumptions
Position value
Unrealized appreciation
Estimated tax, ordinary IRA rollover route
Estimated tax, NUA route
- Ordinary income tax on the cost basis, due now
- Capital gains tax on the appreciation, at sale
- 10% early-distribution penalty on the cost basis
Potential difference
An NUA election only applies when the stock leaves the plan as a lump-sum, in-kind distribution after a qualifying event.
At this cost basis there is no appreciation to treat, so both routes land in the same place.
This tool is educational and simplified. It compares a single lump-sum distribution at the rates you enter, assumes the shares are sold in retirement, and reduces the age-based early-distribution rules to one toggle. It ignores growth after distribution and partial NUA elections. Results are simplified estimates, depend on assumptions entered by the user, and do not predict actual tax consequences. It is not tax or investment advice. Talk to your advisor and tax professional before making any election.
Sherwin-Williams benefits, answered
Does Sherwin-Williams match 401(k) contributions?
Yes. SHW matches the first 6% of pay, up to a cap, so contributing at least 6% collects the full match before anything else. From there, the pre-tax versus Roth split and the 2026 limits ($24,500, plus catch-ups from age 50) decide how hard the plan works for you.
How do Sherwin-Williams RSUs work?
RSU-eligible employees receive performance-based awards tied to company results (EPS and RONAE), paying out at 0 to 200% of target over three years. Vested shares are taxed as ordinary income, with 22% federal withholding for most employees, and can be held or sold during open trading windows.
Does Sherwin-Williams have a pension?
Yes. SHW's Pension Investment Plan contributes between 2% and 7% of eligible earnings each year, with the rate based on your age plus years of service.
What deferred compensation does SHW offer?
High earners can defer income through the Deferred Compensation plan, with payouts beginning at retirement or termination as a lump sum or annual installments over 2 to 15 years. The election is made during enrollment, and the schedule you pick shapes your retirement tax picture.
Can I use NUA on Sherwin-Williams stock in my 401(k)?
Often, yes. At retirement from age 55, Net Unrealized Appreciation rules let you pay ordinary income tax on your cost basis and long-term capital gains rates on the growth when the shares are sold. The sequencing matters: rolling everything into an IRA first can forfeit the treatment.
Do SHW stock options keep vesting after I retire?
At retirement, defined as age 65, or age 55 when your age plus years of service total 75 or more, with 180 days' notice, options may continue vesting and target RSUs continue as well. New grants issued during the notice period are forfeited, so timing the announcement matters.
Keep going on Sherwin-Williams
From the Blog How executives can use NUA to keep more of their company stock gains From the Blog Deferred compensation: the tax timing tool most executives underuse From the Blog Financial planning for executives of publicly traded companies
The team at Tempo has worked with stock-eligible employees at SHW for years. See how we specialize →
The content regarding Sherwin-Williams employee benefits, including the 401(k) and pension plans, deferred compensation, stock options, RSUs, and NUA strategies, is provided for educational purposes only and is not tax, legal, or investment advice. Plan terms change; always confirm details in SHW's official plan documents. Tempo Wealth is not affiliated with or endorsed by Sherwin-Williams. All company trademarks are the property of their respective owners.